Homebuying is always a major financial commitment, but today’s real estate market adds many challenges for the typical homebuyer, requiring more thought and planning than many expect. This article outlines the financial realities today’s homebuyer must consider before starting a property search and how they can lead to more cost-effective decisions about the purchase and its ongoing costs.
As first-time homebuyers face the daunting task of balancing their desire for independence with the expensive proposition of owning a home, the required costs can feel overwhelming. While owning a home provides stability and the ability to build equity, affordability remains a major concern because the advertised purchase price is only the tip of the financial iceberg.
Why Housing Affordability Remains a Major Challenge
Housing affordability affects regions throughout the U.S. However, areas where housing prices have risen faster than residents’ median incomes continue to raise significant concerns. The National Association of Realtors reported that the national median existing-home price was $417,500 in September, up 1.3% from the same period the year before. Listing inventory has increased, but higher borrowing costs continue to dampen affordability for many.
Mortgage interest rates have climbed sharply lately. Freddie Mac reported that the average rate for a 30-year fixed-rate mortgage on October 15, 2026, was 7.40%. Even a quarter of a point difference in interest rates can greatly affect a homeowner’s monthly payments and must be carefully factored into a homebuyer’s decision to purchase.
Whether buying a home is financially realistic today depends on each buyer’s situation, current market conditions, and how those conditions may change in the future. However, viewing homes and properties as good investments should be done with realism and caution.
Understanding Mortgage Options Before Making an Offer
Additionally, buyers must secure appropriate financing. By reviewing a buyer’s income, current obligations, credit report, and savings, a lender will determine how much housing debt a buyer can afford. Many buyers work with a lender to review their financial situation and explore different mortgage options and terms.
Before making a purchase, a buyer should work with a mortgage lender to review the terms of potential financing, including the interest rate, down payment, and mortgage terms and conditions. Using this information, a buyer can establish an affordable purchasing budget. Reviewing all estimates of lender fees to determine the highest and lowest charges, as well as the interest rate, helps to establish the greatest range of potential costs for a buyer.
To determine whether an adjustable-rate mortgage is the best option for you, take stock of your income, what your future holds, and how you will fare if your payments increase. By understanding your costs and financial capacity, you can be better prepared to buy a home.
The Expenses That Go Beyond the Purchase Price
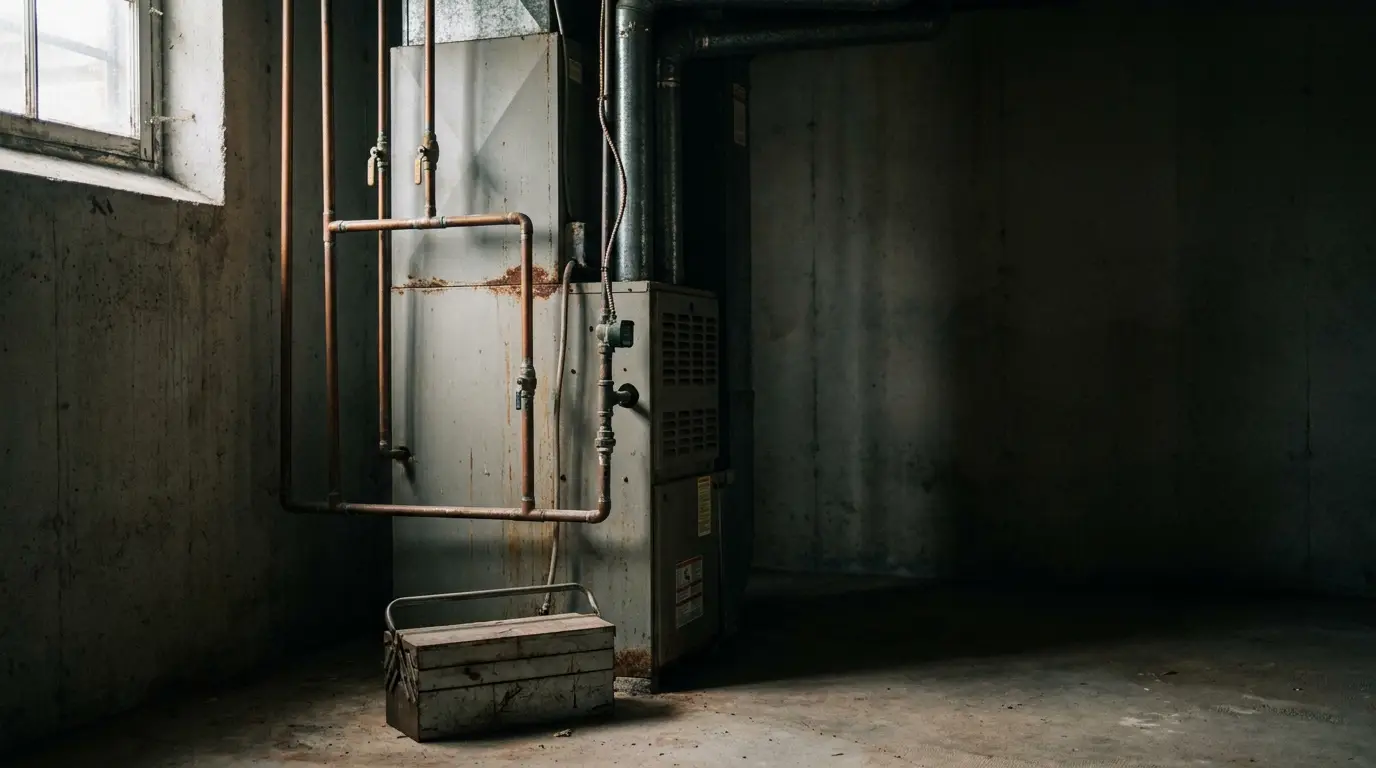
In addition to mortgage payments, such as principal and interest, homeownership comes with many other costs. These costs can include annual property taxes, homeowners’ insurance, and local homeowners’ association fees, where applicable. A homeowner is typically responsible for all maintenance and repairs until the home ages to the point where it requires major repairs, such as replacing the heating system or roof. Other homeownership costs include utilities such as electricity, gas, water, and sewage.
Many people are unfamiliar with closing costs before starting their home search. In addition to the down payment on the home, buyers must consider all the other costs to close on the home, such as appraisal fees, title services, review of loan documents by the lender, and other services that can range in additional cost to the buyer.
The issues associated with unexpected maintenance requirements need more detail. Although a home’s cost can be estimated, few people can predict the extent of unforeseen repairs, including replacing a home’s heating system, roof repairs, and plumbing issues. Homeowners need an emergency fund to handle these unexpected events, and they should maintain it long after they purchase the home.
Why Financial Readiness Matters More Than Market Timing
Even though monitoring current trends can help a homebuyer, no one can accurately predict short-term drops in interest rates and real estate prices. The best approach is to consider your current financial situation and how a real estate investment at today’s market price fits within your budget.
Most people have a good idea of their current and anticipated circumstances over the medium term and should look for a home they can expect to live in for a while after they settle in. Purchasing a home is not suitable for people who expect to move within a year or two and then move again shortly. Depending on individual circumstances, owners may want to wait until interest rates fall before refinancing their mortgage.
It is equally important to recognize that a lower interest rate in the future does not have to mean that refinancing down to a lower rate will allow a buyer to afford a more expensive home. And despite what many homebuyers have been led to believe, refinancing to a lower interest rate will not automatically make more expensive homes “affordable.”